The R&D tax credit is a government incentive that returns part of what a company spends on qualified research. In the US, the federal credit under Internal Revenue Code Section 41 equals 20% of qualified research expenses above a base amount, or 14% under the simpler alternative method. The UK, Canada and Australia offer their own R&D tax credits and incentives, with different rates and rules.
For software and engineering teams, wages tend to be the biggest line in a claim, and a salary only counts for the hours that person actually spent on qualified research. So the time record, logged per employee and per project while the work happens, is what holds the wage figure up when the tax authority starts asking questions. This guide covers the rules as of 2026, a worked calculation, the Form 6765 changes, and what the records need to show.
- What is the R&D tax credit?
- Who qualifies: the four-part test
- What counts as qualified research expenses
- How to calculate the R&D tax credit
- How to claim: Form 6765 and what changed
- The payroll tax election for startups
- Section 174 and 174A as of 2026
- R&D tax incentives outside the US
- Documentation: what reviewers ask for
- Where R&D tax claims go wrong
- Keeping R&D time records in actiTIME
- FAQ
What is the R&D tax credit?
The US federal R&D tax credit, officially the credit for increasing research activities, reduces income tax by a share of qualified research expenses (QREs). It dates back to 1981. The R&D tax credit rate depends on which of two methods a company picks each year:
- The regular credit: 20% of QREs above a base amount built from the company’s historical ratio of research spending to gross receipts.
- The alternative simplified credit (ASC): 14% of QREs above 50% of the average QREs for the three previous tax years, as set out in Section 41(c)(4). A company with no QREs in any one of those three years gets 6% of current year QREs instead.
The credit is generally applied against income tax, according to the IRS. Startups with little or no income tax can use part of it against payroll taxes instead (covered below). Many US states add their own credit on top. North Dakota, for example, uses the federal Section 41(d) definition of qualified research and gives 25% of the first $100,000 above its base amount.
Who qualifies: the four-part test
Industry and company size do not decide eligibility. The activity does. Section 41(d) defines qualified research through four requirements, which the Form 6765 instructions call the four-part test. Each one must be met, and the test is applied separately to each business component (a product, process, software, technique, formula or invention).
-
Section 174A expenses.
The spending must qualify as domestic research or experimental expenditures under Section 174A.
-
Technological information.
The work must aim to discover information that is technological in nature, which means it relies on engineering, physics, chemistry, biology or computer science.
-
A new or improved business component.
The information must be intended for developing a new or improved product, process, software, technique, formula or invention, for function, performance, reliability or quality. Style, taste, cosmetic or seasonal design changes do not count.
-
A process of experimentation.
Substantially all of the activities must be part of a process of experimentation: forming hypotheses, testing alternatives, refining.
Section 41(d)(4) also excludes specific work, even when it feels like research: work after commercial production starts, adapting a product to one customer’s requirements, copying an existing product, market research, routine data collection, routine quality control testing, research outside the US, social sciences and humanities, and research funded by someone else. Software developed mainly for a company’s own internal use has to pass an extra high threshold of innovation test.
For software teams, the dividing line is uncertainty. Chasing an unexplained race condition through several candidate fixes can qualify. Fixing a bug where the ticket already said what was wrong and how to fix it does not, however long it took.
What counts as qualified research expenses
Section 41(b) lists four types of QREs. If a cost is not on this list, it is not a QRE, as the IRS audit techniques guide puts it.
| QRE type | What counts | Rule that decides the amount |
|---|---|---|
| Wages | Wages of employees who perform, directly supervise or directly support qualified research | Only the share of time spent on qualified services; if that share is 80% or more, all wages count |
| Supplies | Materials used and consumed in the research, such as prototype materials | Excludes land, improvements to land and depreciable property |
| Computer rental | Amounts paid to rent or lease computers used in the research | Reported on Form 6765 line 44 |
| Contract research | Payments to outside firms or individuals who do qualified research on your behalf | 65% of the amount paid, under an agreement made before the work starts; payments that depend on success do not count |
The wage rule is where time records matter most. Treasury Regulation 1.41-2 says that when an employee does both qualified and other work, the qualified wage is total wages multiplied by the ratio of time actually spent on qualified services to time spent on all services. The audit techniques guide adds that this ratio is worked out employee by employee, that leave such as sick time stays out of the fraction, and that at 80% or more all of that person’s wages count.
How to calculate the R&D tax credit
The ASC is the easier method to support: it needs three years of QRE history, while the regular credit for an established company needs QREs and gross receipts from a base period in the 1980s, according to the Form 6765 instructions. The calculation below is illustrative: the company, salaries and hours are invented to show the arithmetic, and the rates come from Section 41 and the Form 6765 instructions.
Step 1: turn hours into qualified wages
Take one engineer paid $150,000 a year who logged 2,000 working hours, excluding leave.
That is $45,000 of QREs for one person, and it turns on 250 hours. If nobody logged time per person and per project, nobody can show which side of 80% the engineer was on.
Step 2: apply the ASC
Now assume the company’s total QREs (wages, supplies, computer rental and 65% of contract research) were $400,000, $500,000 and $600,000 in the three prior years, and $900,000 this year.
Sensitivity: every $100,000 of QREs that cannot be supported removes $14,000 of credit before the 280C election, or $11,060 after it. If the company had no QREs in one of the three prior years, the credit would be 6% of $900,000, which is $54,000.
For a corporate R&D tax credit, the 280C line matters because of Section 174A. If a company does not elect the reduced credit, the Form 6765 instructions say it must reduce its deductible domestic research expenditures by the amount of the credit. Electing the reduced credit (79% of the full amount) keeps the deduction intact. The election is made on Item A of an original, timely filed return.
How to claim: Form 6765 and what changed
US taxpayers claim the credit on Form 6765, Credit for Increasing Research Activities, attached to the income tax return. Partnerships and S corporations must file it; partners and shareholders who only receive the credit through those entities report it on Form 3800. The form now asks for a lot more than the arithmetic:
- Section E asks for the number of business components, officers’ wages included in QREs, and whether any new categories of expenses were added. It is required whenever QREs are reported.
- Section G asks for information by business component: its name, the information the company sought to discover, and QREs split into direct research wages, direct supervision wages, direct support wages, supplies, computer rental and contract research.
- Section G becomes mandatory for tax years beginning after 2025, according to the instructions revised in 2025. Filers must cover at least 80% of total QREs by business component, up to 50 components. It stays optional for earlier tax years.
Section G is not required for a qualified small business taking the reduced payroll tax credit, or for a company with total QREs of $1.5 million or less and average annual gross receipts of $50 million or less for the prior three years, reporting on an original return.
Refund claims on amended returns have their own bar. The IRS requires each claim to identify every business component, every research activity performed for it, the individuals who performed each activity and the information each individual sought to discover, plus total wage, supply and contract research expenses for the year.
The payroll tax election for startups
A credit against income tax is worth little to a company that has no taxable profit yet. Section 41(h) lets a qualified small business apply part of the credit to payroll taxes instead. Under the IRS rules:
- A qualified small business has gross receipts under $5 million for the tax year and no gross receipts in any year before the 5 year period ending with that year.
- The election can cover up to $500,000 of credit per year for tax years beginning after 2022, up from $250,000 under the original PATH Act rule.
- The credit first reduces the employer share of social security tax, up to $250,000 per quarter, then the employer share of Medicare tax. Anything left carries to the next quarter.
- The election is made on Form 6765 attached to a timely filed original return. It cannot be made on an amended return.
- The credit is taken on the payroll return with Form 8974, starting with the first quarter after the income tax return is filed.
- A business cannot make the election if it already made it for 5 or more earlier tax years.
Section 174 and 174A as of 2026
From 2022 through 2024, US companies had to capitalize research and experimental expenditures and amortize them over 5 years for domestic research. The 2025 reconciliation law, Public Law 119-21, changed that. As of 2026, the primary sources say:
- Section 174A allows a deduction for domestic research or experimental expenditures paid or incurred in tax years beginning in 2025 or later. A company can instead elect to capitalize them and amortize them over at least 60 months.
- Section 174A treats any amount paid or incurred to develop software as a research or experimental expenditure, according to Internal Revenue Bulletin 2025-38.
- Foreign research expenditures still fall under Section 174 and are amortized over 15 years.
- Small business taxpayers (average annual gross receipts of $31 million or less) could elect to apply Section 174A retroactively to domestic expenditures from 2022 through 2024, within the deadlines the IRS set. Rev. Proc. 2025-28 sets out the procedures and transition options for this and for unamortized amounts.
Section 174A and the Section 41 credit are separate benefits. The first is a deduction for research spending, the second is a credit for a subset of it. The four-part test ties them together, since qualified research must first be a Section 174A expenditure.
R&D tax incentives outside the US
The programs below share the same core idea. They reward technical work that resolves uncertainty, and they want proof of who did that work and when. Rates, thresholds and filing rules differ, so each program below is labelled with its country.
| Country and program | Headline benefit as of 2026 | Filing rule |
|---|---|---|
| US: Section 41 credit | 20% regular or 14% ASC on QREs above a base; up to $500,000 a year against payroll tax for qualified small businesses | Form 6765 with the income tax return |
| UK: merged RDEC scheme and ERIS | 20% taxable expenditure credit; ERIS gives loss making, R&D intensive SMEs an extra 86% deduction and a payable credit up to 14.5% of the surrenderable loss | Only for companies chargeable to UK Corporation Tax |
| Canada: SR&ED | 15% basic investment tax credit; 35% enhanced rate for qualifying CCPCs and eligible public corporations on up to CAD 6 million of expenditures | Form T661, within 18 months after the tax year end |
| Australia: R&D Tax Incentive | Refundable offset of the company tax rate plus 18.5% for aggregated turnover under AUD 20 million; nonrefundable offset of the company tax rate plus 8.5% or 16.5% for others | Register activities within 10 months after the income year ends |
United Kingdom: merged scheme and ERIS
For accounting periods beginning in the 2024 corporation tax financial year or later, the merged R&D expenditure credit scheme and enhanced R&D intensive support replaced the old SME and RDEC schemes. The merged scheme pays a 20% expenditure credit. ERIS is for loss making SMEs whose relevant R&D spending is at least 30% of total spending: they deduct an extra 86% of qualifying costs (186% in total) and can claim a payable credit worth up to 14.5% of the surrenderable loss. HMRC’s eligibility guidance asks the company to explain the work it did to overcome the scientific or technological uncertainty, including its successes and failures.
Canada: SR&ED
The Scientific Research and Experimental Development program gives an investment tax credit at a basic rate of 15%, or 35% for Canadian controlled private corporations (CCPCs) and, for tax years starting after the 2024 Fall Economic Statement changes, eligible public corporations. The enhanced rate now applies to up to CAD 6 million of qualified expenditures, up from CAD 3 million. The CRA says the portion of salary or wages you claim must be based on the time employees spent on SR&ED activities and the tasks they performed, regardless of job title. Claims are due 18 months after the tax year end.
Australia: R&D Tax Incentive
The R&DTI is run jointly by the Department of Industry, Science and Resources and the ATO. Companies generally need more than AUD 20,000 of eligible R&D spending and must register within 10 months after the end of the income year. The ATO sets the refundable offset at the company tax rate plus 18.5% for entities with aggregated turnover under AUD 20 million, and a nonrefundable offset at the company tax rate plus 8.5% (R&D spending up to 2% of total expenses) or 16.5% (above 2%) for everyone else. The government has announced changes in the 2026 to 2027 Budget that start in 2028; until then the current rules apply.
Documentation: what reviewers ask for
The US regulations do not list required documents. Treasury Regulation 1.41-4(d) says a taxpayer must keep records “in sufficiently usable form and detail” to show that the expenses claimed are eligible. In practice, the newer Form 6765 sections and the refund claim rules spell out what that means: wages by business component, split into direct research, supervision and support, and the names of the people who did each activity.
Australia’s record keeping guidance says it plainly: the most accurate records are created at the time the activities are done. It asks for records of what was done, how, when and who carried out the work, and how costs link to eligible activities.
Across these rules, a claim that holds up rests on two kinds of evidence:
- Technical evidence for each business component: the uncertainty at the start, the alternatives tried, test results, failed prototypes, design reviews, and tickets or commits that describe what was unknown.
- Contemporaneous time records per employee and per project: hours logged against the specific project or task while the work happened, separating qualified work from routine work, with leave recorded separately. These records turn payroll totals into qualified wages.
A payroll register shows what someone was paid, and the time record shows what they spent those hours on. When a reviewer questions the wage figure, the answer has to come from the time records. For the payroll side of the file, see our guide to employee payroll records.
InterTalk Critical Information Systems, a Canadian systems engineering company, moved from weekly paper timesheets to actiTIME so it could separate SR&ED eligible work from other work in its claim
Where R&D tax claims go wrong
The research behind a claim can be perfectly real and the claim can still shrink, because the company cannot show how much of it happened. These are the usual weak spots:
-
Timesheets rebuilt at filing time.
Hours pieced together months later from memory are estimates, and they carry less weight than records made at the time. A week of hours typed in on Friday afternoon has the same problem on a smaller scale.
-
Blanket percentages.
“R&D: 80%” for a whole team, with no link to specific projects, is weak evidence, and it happens to sit exactly on the substantially all threshold.
-
Routine work counted as research.
Bug fixes with a known cause, customer specific adaptations and work after commercial release are excluded by Section 41(d)(4), but they often end up in the same project as qualifying work when nothing separates them.
-
Contract research without the right agreement.
Only 65% of contractor payments count, the agreement has to exist before the work, and the part of a fee that depends on success is excluded. Research done outside the US does not count at all.
-
Missed elections.
The payroll tax election and the 280C reduced credit election both belong on the original, timely filed return. Neither can be added later on an amended return.
-
Section G with nothing behind it.
From tax years beginning after 2025, many filers must report wages per business component. A company that only tracked time per person, not per project, has to estimate the split.
Keeping R&D time records in actiTIME
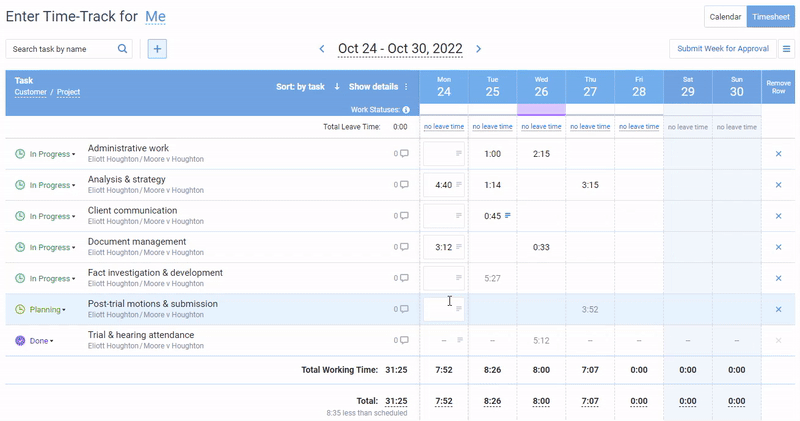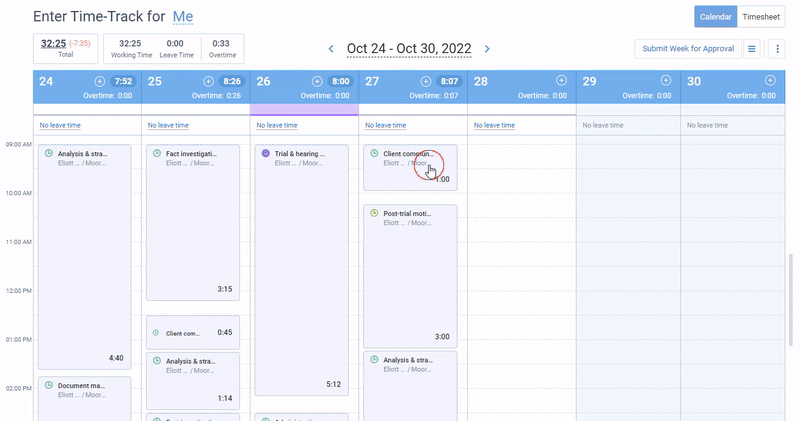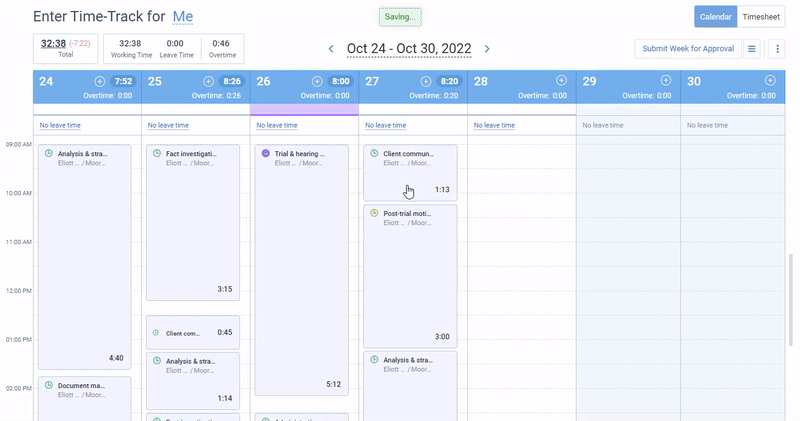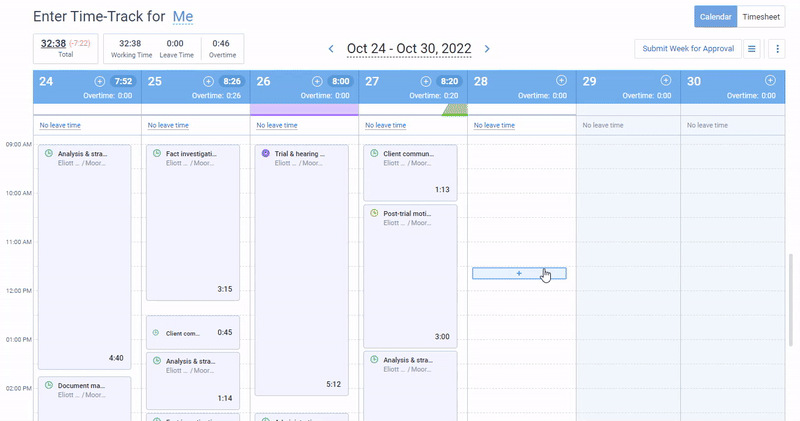
actiTIME does not calculate or file R&D tax claims; your accountant or tax adviser does that. What actiTIME gives you is the time records a claim is built on: hours logged per person, per project and per task as the work happens, exported for whoever prepares the claim. Teams in R&D and engineering typically set it up like this:
- Map projects to business components. actiTIME organizes work as customer, project and task, and the level names can be renamed. A project per business component and tasks per experiment or workstream give you the per component split that Section G asks for.
- Keep qualified and routine work apart. Put research tasks and routine tasks (maintenance, customer adaptations, support) in separate tasks, and use types of work or custom fields to label direct research, supervision and support time.
- Log time while the work happens. People enter hours in a weekly timesheet, a calendar with start and end times, the mobile app, or the Chrome extension timer. Each entry can carry a comment, which is a good place for a ticket link or a note on what was tested.
- Keep leave out of the ratio. Leave is recorded against leave types, separate from work time, so the hours behind the qualified wage ratio are work hours only.
- Approve and lock. Time-Track Approval lets managers review and approve weekly time, and the Lock Time-Track permission stops edits after a period is closed. See how teams run timecard approval.
- Export for the claim. The Time-Track Report groups hours by project, customer, user, date or type of work, and the Time-Track in Detail Report lists every individual entry. Both export as CSV. The Cost of Work Report adds staff costs per user from their cost rates.
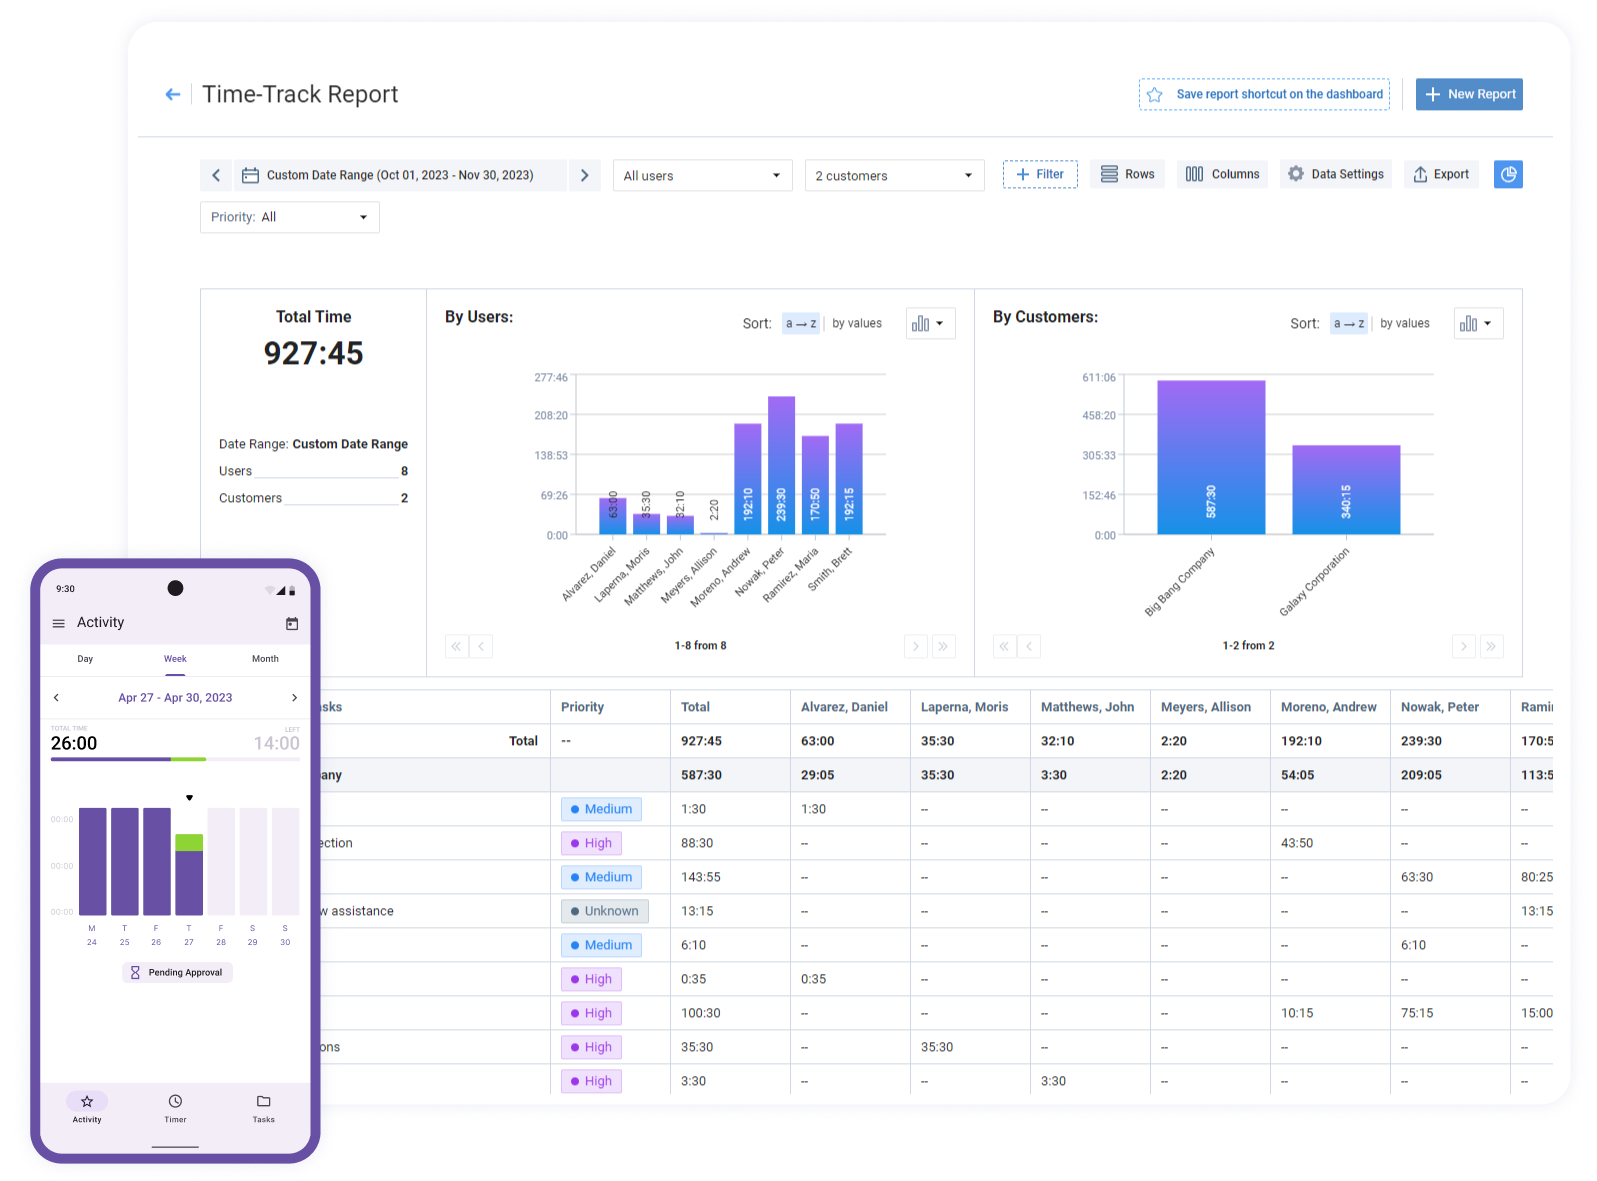
InterTalk’s engineers, for example, document technical progress in their issue tracker and record time in actiTIME across clients, projects and tasks, adding links to the matching tickets in task comments so the eligible time and the technical detail stay connected.
actiTIME is free for teams of up to 3 users, and paid options start from $5 per user per month.


FAQ
Is the R&D tax credit refundable?
The US federal credit is not refundable in cash. It reduces income tax, and a qualified small business can apply up to $500,000 a year against employer payroll taxes instead. Elsewhere, smaller companies can get cash back: through the ERIS payable credit in the UK, refundable SR&ED investment tax credits in Canada, and the refundable offset in Australia.
Can you claim R&D tax credits for past years?
In the US, yes, through an amended return for years that are still open, but the claim must meet the IRS refund claim requirements: business components, research activities, the individuals involved and the information they sought. The payroll tax election cannot be made on an amended return, and the ASC can be elected on an amended return only if no research credit was claimed for that year before.
What is the difference between the R&D tax credit and the Section 174A deduction?
The Section 174A deduction lets a company deduct domestic research and experimental spending, including software development, in the year it is paid. The Section 41 credit is an extra benefit for the narrower set of spending that passes the four-part test. Claiming the full credit reduces the 174A deduction by the credit amount, unless the company elects the reduced credit at 79%.
Summary
The R&D tax credit pays back part of what a company spends on technical work that resolves uncertainty, and the US, UK, Canada and Australia all reward it in different ways. The rates are published by each tax authority. The evidence is up to you, and for wages it comes down to a record of who worked on which project, for how many hours, written down at the time.
Start a free trial of actiTIME with full features for 30 days and set up projects for your research work before the next tax year starts. After the trial, teams of up to 3 users can keep using it for free.